The Director’s Profit Extraction Protocol (2025/2026) – For UK Investors with a PAYE Job
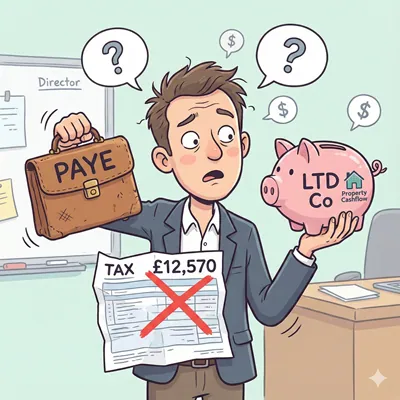
Why the standard £12,570 salary is a tax trap and what to do instead.
Stop. If you run a limited company (especially for your property portfolio) and also have a separate PAYE job, the advice you’re getting is probably wrong.
I see it every day. Well-meaning accountants who tell their clients to “take a £12,570 director’s salary.”
For a director whose only income is from their company, this is fine. For you, it’s a strategic disaster.
You are leaking thousands of pounds in tax, and you probably don’t even know it.
Why? Because that PAYE job has already used your £12,570 Personal Allowance. Every single pound you take as “salary” from your limited company is being taxed at your highest marginal rate—20%, 40%, or even 45% from pound one.
This is not tax-efficient profit extraction. It’s just… extraction.
You need a protocol. This is it.
The Problem: “Total Tax Leakage”
Your goal isn’t to minimise one tax. It’s to minimise “Total Tax Leakage”—the combined sum of all taxes paid by both the company and you.
This includes:
• Corporation Tax (CT)
• Employer’s National Insurance (NI)
• Employee’s National Insurance (NI)
• Income Tax
• Dividend Tax
The £12,570 salary fails this test, because it triggers high Income Tax and Employer’s NI (on the amount above £5,000) for no good reason.
The Real Optimal Salary: £5,000 (Not £12,570)
With the Personal Allowance off the table, your salary decision is no longer about Income Tax. It’s about National Insurance.
• The £5,000 “Secondary Threshold”: This is the magic number for the 2025/26 tax year. If you pay yourself a salary of £5,000, it costs the company £0 in Employer’s NI and costs you £0 in Employee’s NI. It is still a tax-deductible expense, so it saves your company 19% Corporation Tax (£950).
• The £6,500 “Lower Earnings Limit”: The only time you should take more than £5,000 is if your main PAYE job pays less than £6,500. In that tiny-edge case, pay yourself £6,500 from your company. It will cost your company £225 in NI, but it will secure your State Pension credit for the year.
For 99% of you reading this, your optimal director’s salary is £5,000. End of story.
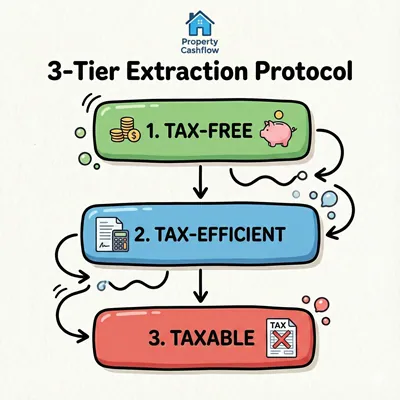
The 3-Tier Protocol for Tax-Efficient Profit Extraction
So, how do you get the rest of your money out? You follow this hierarchy. You must exhaust each tier before moving to the next.
Tier 1: Tax-Free Extraction (The “No-Brainers”)
Extract these first. This is tax-free cash.
1. Reimbursable Expenses: Any money you spent personally for the business. Mileage (45p/mile), train tickets, etc.
2. Trivial Benefits: This is a gift from HMRC. You can give yourself £300 per year in non-cash benefits (like gift vouchers). Each one must be under £50. This is a tax-deductible expense for the company and 100% tax-free to you. If you’re not using this, you’re throwing away £300.
3. Use of Home Office: Claim the £312 per year (£6/week) flat rate. You don’t need receipts. This is another simple, tax-free payment.
Tier 2: Tax-Efficient Extraction (The “Wealth Builders”)
This is where you build real, long-term wealth.
• Employer Pension Contributions: This is the single most powerful tool you have. The company can pay directly into your personal pension. This payment is a 100% tax-deductible expense (saving 19%+ CT). You pay £0 Income Tax and £0 NI on it. It is a pure, tax-free transfer of company wealth to your personal wealth.
• Electric Vehicles (EVs): The Benefit-in-Kind (BiK) rate on pure-electric cars is just 3% for 2025/26. This means a £50,000 EV provided by the company would cost you just £600 in personal tax (if you’re a 40% taxpayer). To buy that car personally, you’d need to extract over £75,000 in dividends. It’s a no-brainer.
Tier 3: Taxable Extraction (The “Leftovers”)
Only after you have maxed out Tiers 1 and 2 do you extract the remaining, post-Corporation Tax profit.
• Dividends: This is your final step. The company has paid its Corporation Tax, and now you pay personal Dividend Tax on what’s left. Because your PAYE job and £5k salary have filled your basic rate band, you will be paying the 33.75% (Higher Rate) or 39.35% (Additional Rate). This is still significantly cheaper than taking it as a salary/bonus, which would cost you 40-45% Income Tax plus 2% Employee NI plus 15% Employer NI.
Critical Compliance Traps for Property Directors
Being a property director has specific, high-stakes traps. Ignoring them is catastrophic.
1. The ATED “Filing-for-Nil” Trap ATED (Annual Tax on Enveloped Dwellings) is a tax on residential properties worth over £500,000 held in a company. The annual charge starts at £4,450.
o The Trap: You might think “I run a rental business, so I’m exempt.” You are. But the exemption is not automatic. You must file a “Relief Declaration Return” with HMRC every year by 30th April to claim your £0 tax bill.
o The Penalty: If you fail to file this “nil” return, HMRC considers you non-compliant. They can (and do) demand the full £4,450 tax, plus late filing penalties. This is a devastatingly simple mistake.
o External Link: Read the government’s guidance on ATED basics here: https://www.gov.uk/guidance/annual-tax-on-enveloped-dwellings-the-basics
2. The Director’s Loan Account (DLA) Trap This is not a tax-extraction strategy. This is a short-term cashflow tool, and it’s dangerous.
o The Trap: If you “borrow” money from your company and don’t repay it within 9 months and 1 day of your company’s year-end, the company must pay S455 tax.
o The Penalty: The S455 tax rate is 33.75%—deliberately set at the same level as the high-rate dividend tax. It’s a temporary tax, but it strangles your company’s cash flow. Be aware of “bed and breakfasting” anti-avoidance rules, too.
o External Link: Understand the rules on Director’s Loans here: https://www.gov.uk/directors-loans
Your Action Plan: Stop Leaking Tax
Don’t be a passive business owner. Your tax strategy is your responsibility
1. Stop taking a £12,570 salary.
2. Start taking a £5,000 salary.
3. Implement the 3-Tier Protocol: Max out Trivial Benefits, Home Office, and Pension contributions before you take a dividend.
4. Check your compliance: Do you own a property >£500k? Set a reminder for your ATED return. Now.
This is the kind of strategic thinking that separates successful investors from busy fools.

Find out what type of investor you are. Take the free investor test to see your real risk profile, then grab the free book with the 12 most powerful ways of making money in UK property.