From Theory to Deal: Your Beginner’s Checklist for NMD Deal Analysis to Secure High-Profit Property Cashflow Deals in the UK
The NMD Analysis Challenge
The promise of No Money Down (NMD) property investing is exciting: building a portfolio without relying on your own savings. NMD, however, is not about luck; it’s about leverage and rigorous analysis.
When you use other people’s money (OPM), the stakes are higher, and the need for a bulletproof deal is non-negotiable. Traditional deal analysis (Purchase Price vs. Rent) isn’t enough. You must analyze the deal’s intrinsic value and the viability of the creative finance structure itself.
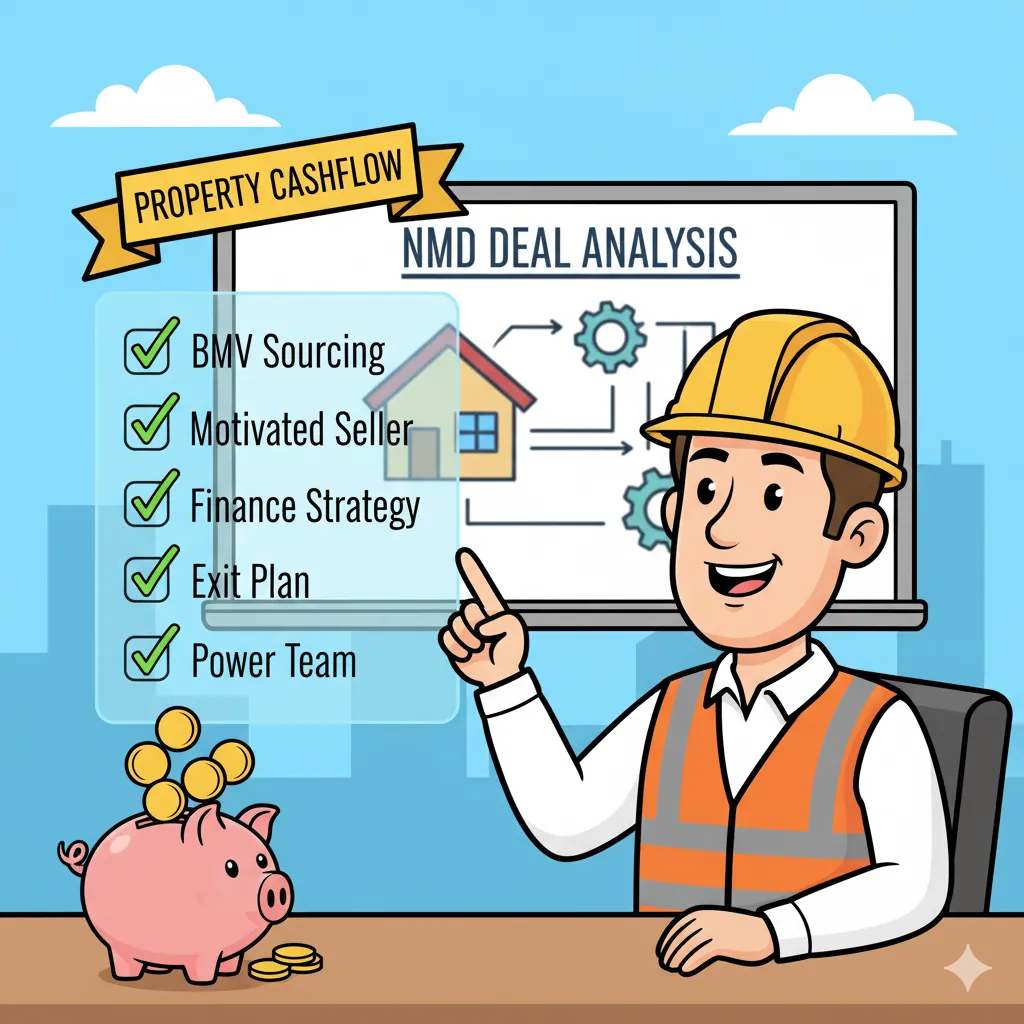
Your ability to confidently assess these opportunities—using a systematic NMD deal analysis checklist—is the biggest asset you bring to any partnership. Here is the step-by-step blueprint to ensure your next creative finance deal delivers maximum Property Cashflow.
Phase 1: The Core Deal Metrics (The BMV Test)
The appeal of SA is driven by two factors that beat almost any Buy-to-Let (BTL) model: superior tax efficiency and exponentially higher yields.
The foundation of every NMD deal is a deeply discounted property. If the property doesn’t stand alone as a great deal, the NMD structure only adds risk.
1. Purchase Price vs. True Market Value (TMV)
•Question: Is the purchase price at least 15-20% Below Market Value (BMV)?
•Action: Get three comparable sales (sold in the last 6 months, within 0.5 miles). You must be able to demonstrate to a potential Joint Venture (JV) partner or a lender that the price is discounted. This discount is your margin for error.
2. After Refurbishment Value (ARV) & Refurb Cost Buffer
•Question: After renovation, what is the guaranteed market value, and is the renovation budget realistic?
•Action: Get a detailed quote from a builder. Crucially, add a 15% contingency buffer to the refurb cost. If the deal doesn’t stack up with the contingency included, move on.
3. The Net Yield Non-Negotiable
•Question: What is the projected Net Yield after all running costs, including mortgage, insurance, management fees, and a 10% maintenance reserve?
•Action: For HMO or Serviced Accommodation (SA) NMD deals, aim for a minimum 10% Net Yield. This high threshold ensures there’s enough Property Cashflow to withstand void periods and pay a passive money partner a solid return.
Phase 2: The NMD Structure Analysis (The Money Test)
This phase analyses the specific creative finance mechanism you are using, be it a Joint Venture, a Lease Option, or Vendor Finance.
4. Cost of Capital (The Partner’s Cut)
•Question: How much does the money cost? (Interest rate, profit split, or fixed fee.)
•Action: If a JV partner funds the deposit/refurb, determine the split. If it’s a 50/50 profit split, ensure your 50% is enough to cover your time and effort. If it’s a fixed interest rate, ensure the deal still cash-flows aggressively even at 1-2% higher interest than projected.
5. Security and Repayment Structure
•Question: How is the partner/vendor secured, and how is their capital repaid?
•Action: In a JV, capital is almost always repaid via a Refinance (the ‘R’ in BRRRR). Calculate the exact amount of capital you can pull out at the target ARV and ensure it covers the OPM plus all acquisition costs. The deal fails if the refinance doesn’t release enough funds to pay back the initial capital.
6. The Exit Strategy Timeline
•Question: How long is the NMD structure required before a standard exit can occur?
•Action: If it’s a flip, the exit is the sale (6-9 months). If it’s a BRRRR, the exit is the refinance (12-18 months). Be honest about the timeline. Long delays in NMD deals can significantly increase the cost of bridging or private finance and sour the partner relationship.
Phase 3: The Risk & Compliance Review (The Safety Test)
You must de-risk the deal not just for yourself, but for your funding partner, whose trust is your primary currency.
7. Partner Due Diligence (Yours and Theirs)
•Question: Have you and your partner clearly defined roles, responsibilities, and decision-making authority?
•Action: A lack of clarity sinks JVs. Draft a detailed, non-binding Heads of Terms (HOT) document covering who does the sourcing, who manages the build, and who handles the letting. If you can’t agree on the HOT, don’t sign the legal agreement.
8. Legal Structure and Documentation
•Question: Is the agreement legally binding and does it protect both parties?
•Action: NEVER use template documents for NMD deals. Use a specialist property solicitor. The preferred structure is an SPV Limited Company with clear shareholder agreements and potentially debentures or fixed charges to protect the money partner’s capital against the asset.
9. Local Compliance Check
•Question: Does the property comply with local council regulations for your planned strategy?
•Action: Check the local council’s website for Article 4 Directions (essential for HMO/SA conversions) and any specific licensing requirements (HMO or Short-Term Let registration). A great deal can become worthless overnight if it falls foul of an unexpected regulation.
Your Knowledge is the Deposit
Using this Beginner’s Checklist for NMD Deal Analysis, you move from chasing dreams to executing a calculated strategy. Remember, in NMD investing, your personal capital is replaced by your knowledge and credibility.
By rigorously checking the market value, the financing structure, and the legal safety of every deal, you not only protect yourself but you build the reputation necessary to attract more capital, allowing you to scale your Property Cashflow empire exponentially.
Serviced Accommodation in 2025 is not passive; it is systemised. The shift from being a hands-on landlord to a strategic business owner is the only way to reap the huge rewards this sector offers.
Embrace the compliance, invest in the right systems, and structure your business for FHL benefits. Do this, and you will secure a far greater, more flexible stream of Property Cashflow than any traditional rental model can provide.
Ready to stop guessing and start analysing your NMD deals with the confidence of a seasoned pro?
The team at Property Cashflow provides expert, in-depth deal analysis and structuring support, ensuring your NMD projects are de-risked and maximised for profit. We help you transition from the checklist stage to closing the deal.
We specialize in high-cashflow investments, including NMD and creative finance, in the Liverpool and Wirral areas, understanding the specific Article 4 rules and market dynamics required for your success.
Stop leaving your next great deal to chance. Start analysing it right.Contact us today to discuss auditing your next NMD opportunity: Email: info@propertycashflow.co.uk

Find out what type of investor you are. Take the free investor test to see your real risk profile, then grab the free book with the 12 most powerful ways of making money in UK property.